Many of the people who lose money to scammers have spent decades making smart financial decisions. They’re skeptical of strangers and careful with passwords, and many assume they’d spot a con. Because protecting what you’ve built is part of the planning work we do at Thrive Wealth Management, we frequently discuss financial cybersecurity with the families we work with.
If you’ve ever assumed a scam couldn’t happen to your family, you’re not alone. Many of these schemes are built to create pressure, often through someone who sounds official and already has some of your personal details. Below, I’ll share some warning signs we often walk clients through and a few protections your family may consider.
The Pattern Behind Many Costly Attempts
The FBI’s 2025 Internet Crime Report shows Americans reported $20.9 billion in losses in 2025, with $7.7 billion reported by adults age 60 and older. Many of the attempts behind those numbers share four warning signs:
- Borrowed authority: The caller claims to represent the IRS, the FBI, your bank, or your custodian, often with documents that look real and personal details gathered from public records.
- Manufactured urgency: A short deadline that leaves no time to verify.
- An instruction to stay silent: You’re told not to involve your family or your advisor.
- A new destination for the money: The request points to an unfamiliar account, or a familiar payment arrives with new instructions from a real but hacked email address.
Requests to pay with gift cards or through a cryptocurrency ATM are another potential signal, and the FTC warns against paying anyone who claims to be from the government this way. A legitimate institution can typically wait a day while you verify, but most scammers can’t afford to.
A Rule Borrowed From Fire Safety
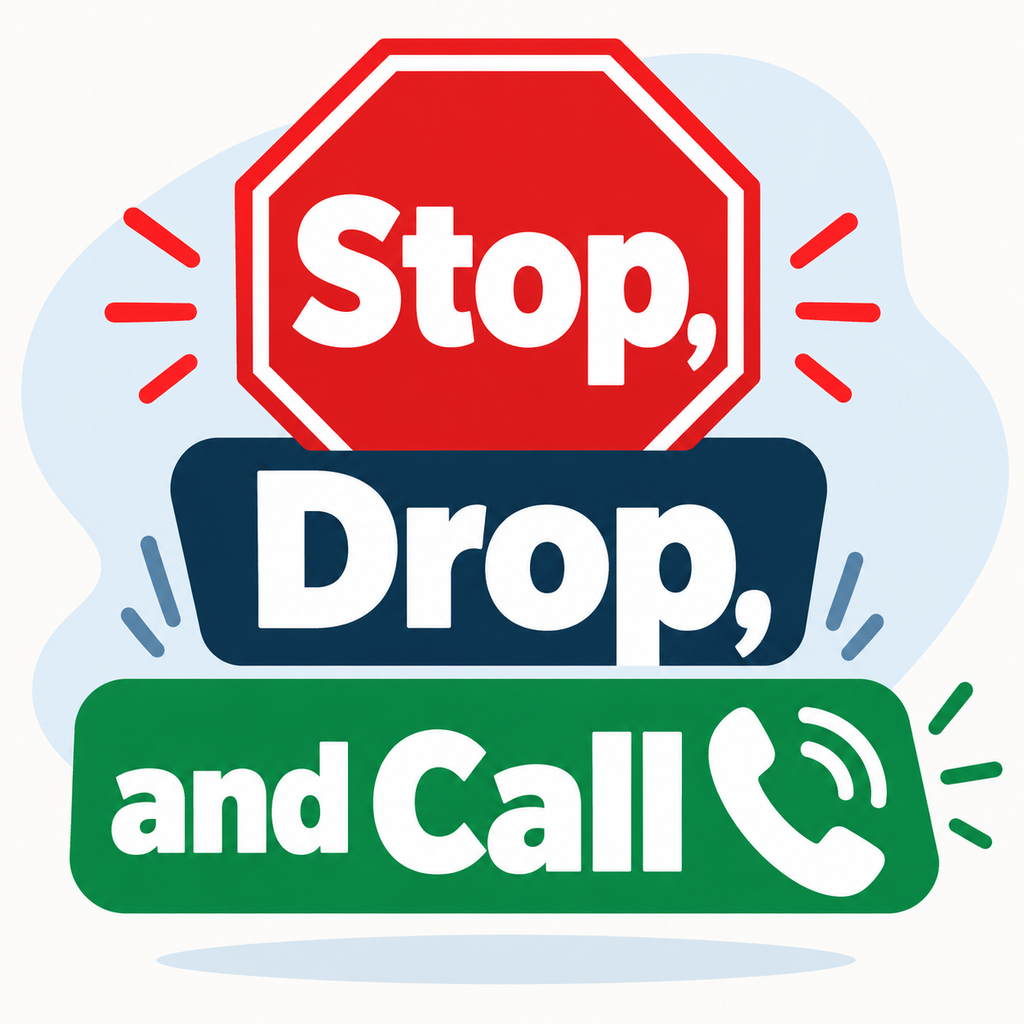
Borrowing from “Stop, Drop, and Roll,” when something feels off, “Stop, Drop, and Call.” When in doubt, we suggest clients stop the conversation, drop the connection, and call a known legitimate contact to verify the situation.
Certain transactions, such as real estate closings, deserve extra attention, since title companies have become a recurring target for wire fraud. Bad actors can infiltrate their email systems and change wiring instructions to re-route the settlement proceeds. Before sending closing funds, consider calling the title company at a number you’ve verified independently and ask your closing agent whether a certified bank check is an option.
Controls Set in Advance
Many large transfers, like a home purchase or help for an adult child, happen only occasionally, so many families haven’t built a habit of verifying them. A few protections can be set up before anyone calls:
- A household pause rule: Waiting a day before any large transfer can give everyone room to verify, and it usually costs very little.
- A family verification question: A question only a relative could answer, like the name of Grandma’s dog, can help confirm a caller now that AI tools are more capable than ever of imitating a familiar voice.
- A trusted contact on investment accounts: Your custodian can reach this person if activity looks unusual, but the trusted contact can’t move your money unless a separate authorization is granted.
- Two-step login on your email: A second login step can make it harder to hijack the account that often carries payment instructions.
If one spouse has handled the finances for years, planning together can give the household a second person who can spot a request that doesn’t fit.
A Second Set of Eyes
An advisor who knows your household may notice when a request doesn’t sound like you, and our team has its own verification steps before money is sent to a third-party.
If you’d like to talk through protections that may fit your family, schedule a meeting by calling (215) 376-5530 or emailing.
Frequently Asked Questions About Financial Cybersecurity
Will the IRS or FBI ever call and tell me to move my money?
No (at least not out of the blue). Federal agencies, including the IRS and FBI, don’t call demanding that you move money to safeguard it or pay with gift cards or cryptocurrency. A caller who does is almost certainly impersonating the government. You can hang up and contact the agency at a number you look up yourself from a third-party resource (like Google).
What are some of the warning signs of a financial impersonation scam?
Common warning signs include:
- Borrowed authority: A caller claiming to represent a government agency or financial firm
- Urgency: Pressure to act before you can verify
- Secrecy: Instructions not to tell family or your advisor
- A new destination: An unfamiliar account or changed payment instructions
Is it safe to wire money for a real estate closing?
Wiring closing funds can be safe, but real estate transactions are a frequent target for wire fraud. Before sending money, consider calling your title company at a number you’ve verified independently instead of one from an email. You may also ask whether a certified bank check is accepted.
What is a trusted contact on an investment account?
A trusted contact is a person you designate that your custodian may contact if it suspects financial exploitation or can’t reach you. A trusted contact generally can’t move your money. At Thrive Wealth Management, we encourage clients to consider naming one as an added layer of protection.
What should I do if I think I sent money to a scammer?
Contacting your bank or custodian right away may improve the chance of stopping or recalling a transfer. You can then report the fraud to the FBI at ic3.gov and to the FTC at ReportFraud.ftc.gov. Letting your advisor know can also help them review your other accounts.
This material is provided for informational and educational purposes only, should not be viewed as an exhaustive discussion of the topics presented, and should not be construed as individualized advice for any reader’s personal circumstances. For guidance on how these matters may impact your financial plan or investment portfolio, please contact your Thrive Wealth Management, LLC representative. While the information presented is believed to be factual and up to date, Thrive Wealth Management, LLC does not guarantee its accuracy and, due to various factors, including but not limited to changing laws and regulations, this information is subject to change. All expressions of opinion reflect the judgment of the authors as of the date of publication.
Past performance does not guarantee future results. All investing comes with risk, including risk of loss.